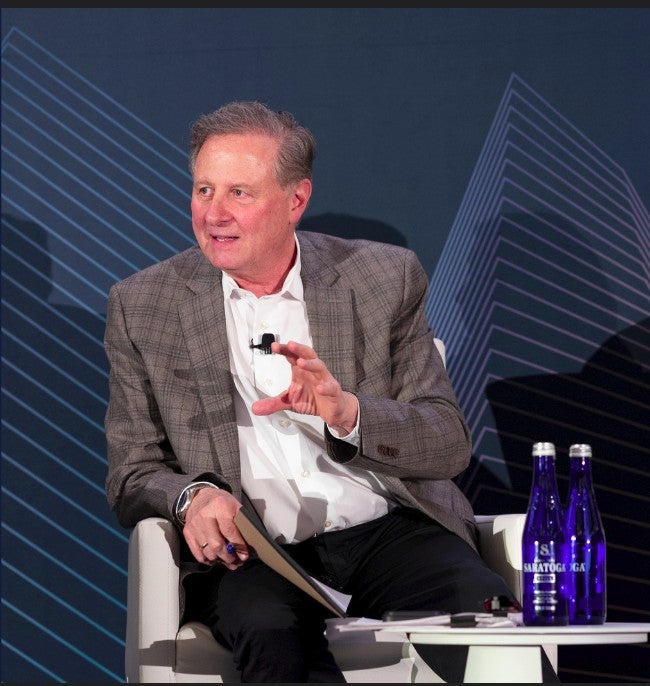
As Prosperity Partners enters its next growth chapter with Lightyear Capital, Allan Koltin, CEO, Koltin Consulting Group, Inc and Jeremy Dubow cpa, chief executive officer, Prosperity Partners discuss market dynamics, deal timing, and advisory trends with Zoya Malik, editor-in-chief, IAB.
Zoya Malik (ZM): Prosperity was among the earliest accounting firms to embrace private equity, and now it’s transitioning from Unity partners to Lightyear Capital. What makes this transaction strategically significant, and what does it say about the evolution of PE-backed accounting platforms in today’s market?
Allan Koltin: Strategic significance: it’s a point for the PE model and a win/win/win – this is a successful PE to PE transaction, with Prosperity remaining the same firm for its employees and clients before and after the transaction. It has proven that a great outcome for a PE investor can also be a great outcome for:
- Firm partners, whether they were developed internally or acquired or sold their business to Prosperity, are now part of an incredible growth journey and have seen the value of their equity incentives and rollover equity grow materially and be validated by the market.
- Staff – who shared in the equity value growth to the tune of $18 million through Prosperity’s Employee Purpose Plan.
- Clients – who have access to a growing team of incredible professionals (who are motivated to do what’s best for clients because they know that will create success for the firm) and are getting access to additional services and professionals via Prosperity’s strategic M&A, which are vetted by Prosperity to an incredibly high standard
What does it say about the evolution of PE-backed platforms:
Go deeper with GlobalData
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
- Size – at Unity’s investment, Prosperity was the smallest PE platform in the industry. It has proven that size doesn’t matter and rather the quality of the team, the leadership, the client base, the service offering and service quality are what makes a platform.
- Positioning in the market – Prosperity has a earned a great reputation in high-net-worth and ultra-high-net-worth services. Having a type of client or type of service that you can hang your hat on is important. If your strategy is to be all things to all clients, you risk not being the best firm to serve any client.
- Importance of growth and leadership – Prosperity has delivered double-digit organic growth consistently and has had success in M&A on top of that. Lightyear is betting on this team to keep that growth up and even accelerate.
ZM: The accounting advisory market has seen sustained consolidation over the past few years. Why do you think this was the right time for Prosperity to bring in a major majority investor, and what broader market conditions made this deal particularly timely?
Allan Koltin: This is less about market conditions and more about what Prosperity has accomplished. During its partnership with Unity, Prosperity rebuilt its technology stack, acquired several add-ons to bring on additional capabilities and to leverage the value of its platform, and throughout it all it was able to maintain outstanding organic growth. Prosperity accomplished what it set out to do when it partnered with Unity, and it was time to deliver liquidity to Prosperity’s team and reward their efforts.
That said, the market is always a factor in these transactions. What we have seen is the demand for best-in-class firms in the industry continues to be incredibly strong. There are far more interested buyers for these firms than there are firms available to be purchased or open to receiving investment. What that means is the best firms have leverage to pick their timing, pick their investors and have some protection from the ebbs and flows of market conditions.
ZM: You’ve described Prosperity’s evolution from a specialised tax business into a national advisory platform. Which parts of the business do you believe hold the greatest long-term value today; tax advisory, client accounting services, transaction support, or their high-net-worth focus, and why?
Allan Koltin: All of those are valuable on their own, what makes Prosperity an amazing business is how they come together. It’s about the whole being greater than the sum of the parts. One way Prosperity has accomplished that is with its high-net-worth focus and being disciplined about adding teams and service lines that can serve that type of client. This is a high-touch client that needs to know there is a person they can reach, that they trust to be an expert, and will be responsive to their needs. That trust-based relationship is valuable because it creates a sticky relationship and gives firms like Prosperity the best chance to use technology to improve client service without being disrupted by that same technology.
ZM: Lightyear highlighted recurring revenue, technology investment and strategic M&A as key attractions. Are these now the defining characteristics private equity firms are prioritising when evaluating accounting and advisory platforms, and how has that investment thesis changed over the past few years?
Allan Koltin: I think PE firms are really interested in how well firms are insulated from AI disruption and how prepared they are to use AI themselves. Firms that can demonstrate both will generate lots of interest.
Jeremy Dubow: As a firm, we have been focusing on all three of those over the last few years. We’ve been building a business around recurring revenue for a long time, along with many others, that’s not new in our industry. But when we partnered with Unity Partners in 2023, we were able to accelerate our efforts in technology & M&A specifically. Our success in both those areas contributed to now being the right time for us to partner with Lightyear, set new goals, and start working to achieve them. Retaining clients by delivering a high-touch, excellent service and creating that recurring revenue will continue to be important for us, as will technology, including using AI to improve our business, and M&A. In the past, these may have been ways to differentiate, but now they seem increasingly to be table stakes to compete.
ZM: Prosperity completed nine strategic acquisitions under Unity’s ownership. As the business enters its next chapter, where do you see the biggest opportunities for inorganic growth, and are there still attractive acquisition targets available, in this increasingly competitive market?
Allan Koltin: Prosperity has done 10 add-ons and closed one more just before the Lightyear deal that it has not publicly announced yet.
It’s a large, fragmented market, which is one reason PE is interested in accounting generally. What that means is that even though it seems like lots of M&A is going on, there are tons of independent firms that are not ready or not willing to consider a transaction yet, but firms are coming to the realization that they have to at least consider it all the time. That will generate new opportunities for a long time to come as long as valuations hold up.
As independent firms looks to make investments in technology, or find ways to share in firm equity value with their teams, or look to pursue their own M&A strategies, some will find it’s hard to do it all; and partnering with a firm that has already figured these things out may look more attractive.
ZM: From your perspective advising on this transaction, how aligned were Prosperity and Lightyear from the outset? Beyond valuation, what were the key strategic factors that convinced you this partnership would create long-term value?
Allan Koltin: Lightyear is not new to the industry – it invested in and recently had a successful exit from Schellman. That’s a different business from Prosperity, but it made Lightyear’s learning curve to understand Prosperity, really short.
They were really well aligned from the outset because they agreed on what makes Prosperity a valuable business today: client trust and great people. If you have a great team from the bottom up and you’ve earned your clients’ trust year after year, that’s a strong foundation to keep building on.
ZM: The high-net-worth and family office advisory market continues to attract significant investment. Do you expect the segment to remain one of the strongest growth areas for accounting firms, and what structural trends are driving investor confidence?
Allan Koltin: Wealth continues to be a theme that PE firms are pursuing, and accounting is only one industry of a many where they are pursuing it.
These customers are generally willing to pay up for a premium service, so attracting these types of customers is one way to make sure the best people in an industry are getting paid well to be the best. It’s a hard thing to start from scratch, but if you can do it, you can create a virtuous cycle of attracting these clients, allowing you to pay the best people to provide the best service to them, and having the best people attracts more of these clients, and on and on.
To touch on AI again, that’s the type of client relationship that PE believes is most insulated from technology. You can use technology to improve your service, of course, but these types of clients generally won’t trust an AI chatbot to do their tax returns or provide advice on complicated tax matters.
Jeremy Dubow: We do expect it to remain a strong source of growth in our market and for Prosperity. Part of the reason is that it’s a segment of the market where you can use technology to be better, but there’s always a need for a human advisor that has earned the trust of our clients. What AI is really good at today is repeatable tasks that don’t require judgement. Wealth tends to create complexity, and that complexity requires human judgement. We think we are well positioned to leverage AI in our business to allow us to better serve clients. We want to free up our people to be advisors to clients using expertise across our firm and the best technology, rather than asking our people to spend lots of time entering data into software.
ZM: Employee ownership has become a notable feature of Prosperity’s private equity journey, with the Employee Purpose Plan distributing substantial proceeds to staff. Do you see broader employee participation becoming an increasingly important component of successful PE backed accounting firms, particularly when competing for talent?
Allan Koltin: As there are successful liquidity events that produce tangible value for employees, that will put pressure on firms that aren’t doing this to start, or risk losing talent. It’s one-way independent firms that don’t have the cap table flexibility to share equity, are going to have to find a way to compete or risk losing talent in a talent-constrained industry.
Jeremy Dubow: We see it as a competitive tool to ensure we attract and retain the best talent. I expect it to become more common, but the ultimate value of it depends on the success of the firm. Firms that struggle to grow enterprise value will find that whether they are generous with equity incentives or not, if it doesn’t produce value for employees, it will not do the job of attracting and retaining talent. It works best when you put the incentives in the hands of talented people, allow them to contribute to growing equity value, and then ultimately deliver that value as promised.
ZM: You have advised many of the accounting professions landmark transactions. How does this deal compare with others you’ve worked on in terms of sophistication, strategic positioning and what it signals for the next phase of consolidation across the accounting and advisory sector?
Allan Koltin: Although a few years ago Prosperity may have been a boutique, it is now a top 100 firm, so the sophistication involved in this transaction was very high. The largest and most highly regarded law firms and financial advisors were involved in the transaction such as Guggenheim served as a financial advisor to Unity and Prosperity, Koltin Consulting Group served as a financial advisor to Unity and Prosperity, Kirkland & Ellis served as legal counsel to Unity and Prosperity and Davis Polk, served as legal counsel to Lightyear.
A transaction this successful, is focused on delivering results for investors, management, partners, staff and also clients who will see benefits of additional services and motivated professionals who are excited to work for Prosperity and fully engaged in delivering value for clients because the staff know they will share in the ultimate benefit of doing the right things to build a firm with enduring value.
Growth is a huge driver of value, if you’re growing, that is usually the result of delivering great service to clients and being a destination for talent and for firms looking to join a PE-backed platform.
ZM: As Prosperity prepares for its next phase with Lightyear, what message do you think this transaction sends to independent accounting firms that are weighing private equity partnerships? Are we entering a more mature phase of the market, or is there still considerable runway for platform creation and M&A led growth?
Allan Koltin: The message independent accounting firms should be hearing is, “look at how well this can work when it’s done right”. That doesn’t mean it’s right for every firm, but they should recognise that this model is not only here to stay, but successful PE to PE transactions that deliver value broadly to teams are only going to attract even more PE interest.
Prosperity was able to deliver $18 million of value broadly across all employees as part of this transaction, through its Employee Purpose Plan. Firms that plan to remain independent should be thinking about what they will need to do to be competitive in the market for talent going forward. The market is maturing, but it’s a big market and there remains huge opportunity for M&A growth for firms that have the capability and the capital to do it.
The pace of platform creation is slowing a little, it’s not easy to be the platform, there might be a lot of work for a firm that wants to be a platform before they are actually ready for it.
ZM: How has your expertise evolved over the past decade alongside the Private Equity market’s evolution in accounting? What have been the personal career learnings and insights on market nuances across jurisdictions?
Allan Koltin: Our expertise, learning, and insights have evolved since PE entered the accounting profession in the following ways – we have gone from doing only mergers (historically there was no cash at closing and ‘seller’ only receiving deferred compensation to now doing acquisitions with the ‘seller’ receiving significant cash (with favorable tax treatment) and rollover equity that significantly appreciates in value vs. the CPA firm’s previous equity that had virtually no appreciation). Because of the increase in CPA values, our M&A and Advisory business has tripled both in size and number of deals we advise on each year. We have gone from advising on 10-12 deals in a year to 30-36 deals annually.
We have seen the culture change with PE entering the accounting profession. PE takes on much more risk – investment, capital is deployed faster and on a much larger scale. Also, PE is willing to make tougher decisions (and more of them) than what we historically could do within the limitations of the traditional CPA firm partnership model.

Frequently asked questions
-
Why are PE investors interested in accounting firms?
There is a demand for best-in-class firms in the industry continues to be incredibly strong. There are far more interested buyers for these firms than there are firms available to be purchased or open to receiving investment.